Haven Retirement Readiness

Structured financial planning consultations for professionals within roughly ten years of retirement—mapping income gaps, employer benefits, and Thailand-based tax considerations before you lock in a leave date.

+66-42-218-534

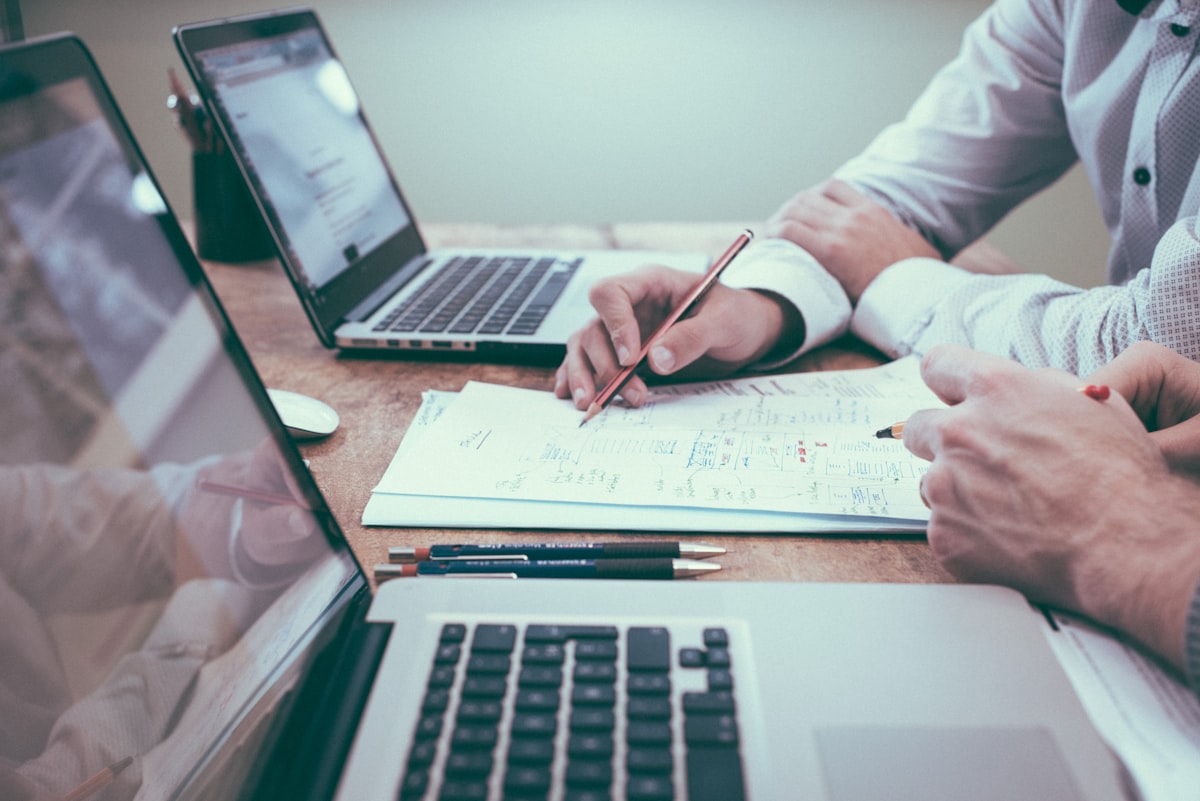
Advisor reviewing retirement cash-flow notes at a desk
Warm-grade editorial photo — planning workspace
Hands comparing printed charts about savings and drawdown timing
Late-career planning often starts with clarifying what must be funded before employment income slows.

Where consultations concentrate

Each engagement stays anchored to decisions that matter when payroll is still steady but the retirement window is visible.

Income bridge years

We model how salary, bonuses, and part-time work might taper so you see when withdrawals would need to begin.

Provident-fund rules and informal family support are noted where you raise them—without promising specific fund returns.

Healthcare reserves

Out-of-pocket medical costs often rise after employer coverage ends; we stress-test buffers rather than guessing a single premium.

Estate clarity

Beneficiary designations and property titling are reviewed at a planning level, with referrals to legal counsel when deeds need changing.

How a planning cycle unfolds

Our process-led conversations follow a repeatable sequence so you always know what data to gather next.

Step 1

Intake and constraints

You share employment timeline, dependants, and existing statements. We flag gaps—missing pension statements, unclear stock vesting—before any projection.

Step 2

Baseline projection

We build a conservative cash-flow view using your supplied balances and assumed spending bands, separating must-pay costs from discretionary goals.

Step 3

Decision memo

You receive a written summary of trade-offs—working longer, relocating within Thailand, adjusting drawdown order—so choices are documented, not improvised.

Step 4

Review rhythm

Markets and health change; we schedule follow-up checkpoints aligned to your stated retirement horizon, not a generic annual calendar.
Retirement readiness is less about chasing a headline number and more about knowing which expenses your late-career income still covers—and for how long.

Who benefits—and who may need a different specialist

Well suited

Managers and specialists in Udon Thani or nearby provinces who want a documented plan before reducing hours.

Less suited

Active day-traders seeking trade signals, or households needing urgent debt restructuring without stable income.

Next step

Send an inquiry describing your target retirement window; we reply with whether a consultation fits and what documents help.

Open the contact form